Cash Flow Statement: Concept, Meaning, Principles, and How to Prepare It Under Circular 200 | Wotech Electronics
Vũ Khôi
Tác giả tại Wotech Electronics Blog
Cash Flow Statement: Concept, Meaning, Principles, and How to Prepare It Under Circular 200
Vũ Khôi
Author at Wotech Electronics Blog
The cash flow statement is one of the four basic financial statements, alongside the Balance Sheet, the Income Statement, and the Statement of Changes in Equity. It helps managers control a company's cash flows. It is therefore a very important task that demands accuracy and full compliance with accounting standards.
SimERP will share the concept, purpose, and a roundup of the principles. In addition, the article shows how to prepare a cash flow statement in the most compliant way with Circular 200.
What is the cash flow statement?
Definition
The cash flow statement, also known as the statement of cash flows, presents the cash inflows and cash outflows of a business over a given period. From it, managers can assess and control cash flows, and it also helps the business evaluate how effectively those flows are being used.
The cash flow statement consists of 2 basic parts:
Cash inflows:
-
Customer payments for goods or services
-
Bank deposit interest
-
Savings interest, investment returns
-
Investment from shareholders
Cash outflows:
-
Costs of purchasing shares, goods, raw materials, and tools for production and business
-
Payroll costs, facility rent, and daily operating expenses
-
Purchases of fixed assets (for example, machinery, office equipment, etc.)
-
Return distributions
-
Corporate income tax, personal income tax, value-added tax, and other taxes and fees
Based on business activity, cash flows can be classified as follows:
-
Operating activities: includes cash inflows and outflows related to producing and selling the company's goods and services
-
Investing activities: includes cash inflows and outflows related to investing in and liquidating assets and long-term financial investments
-
Financing activities: includes cash inflows and outflows related to raising capital from owners and creditors, repaying creditors, paying dividends to shareholders, distributing returns to investors, and buying back shares
Meaning of the cash flow statement
The cash flow statement is a key foundation of corporate financial management. It provides information on the sources, purposes, and amounts the business has received and spent during the period, showing the relationship between net cash flow and profit — where net cash flow reflects the difference between cash inflows and outflows, and profit reflects the difference between revenue and expenses.
Through the cash flow statement, managers can assess the company's ability to generate cash internally and externally, as well as its ability to repay debts on time. It is also an important basis for forecasting the company's future cash flows.
Guide to the cash flow statement under Circular 200
Principles for preparing the cash flow statement
The cash flow statement is one component of a company's financial statements. It is a mandatory financial statement prepared at the end of each fiscal year. Under Circular No. 200/2014/TT-BTC (Circular 200) of the Ministry of Finance, there are 2 methods for preparing the cash flow statement: direct and indirect. Preparing the statement under each method must follow these principles:
Direct method cash flow statement
Presents and determines the cash inflows and outflows of operating activities by directly analyzing and consolidating receipts and payments item by item, based on the company's general and detailed accounting ledgers.
Advantages
- Directly presents information on cash received/paid from operating activities
Disadvantages:
-
Does not show the relationship between operating results and the cash flow results of those operations
-
Figures are harder to verify and reconcile than those in other types of reports
Line items for preparing the statement:
-
Cash received from sales of goods, service provision, and other revenue (Code 01): Debit balances of accounts 111, 112 corresponding to the credit side of accounts 511, 131, 3331, 515, 121…
-
Cash paid to suppliers of goods and services (Code 02): Credit balances of accounts 111, 112 corresponding to the debit side of accounts 331, 131, 152, 156, 138, 153, 154, 621, 642, 641, 632, 338, 242.
-
Cash paid to employees (Code 03): Credit balances of accounts 111, 112 corresponding to account 334.
-
Interest paid on borrowings (Code 04): Credit side of accounts 111, 112 corresponding to the debit side of accounts 335, 635.
-
Corporate income tax paid (Code 05): Credit side of accounts 111, 112 corresponding to the debit side of account 3334.
-
Other cash receipts from operating activities (Code 06): Debit side of accounts 111, 112 after reconciliation with the credit side of accounts 711, 133, 141, 244, 136, 331.
-
Other cash payments for operating activities (Code 07): Credit side of accounts 111, 112, 113 corresponding to the debit side of accounts 811, 161, 244, 333, 338, 344, 352, 353, 356.
→ Net cash flow from operating activities (Code 20) = Code 01 + Code 02 + Code 03 + Code 04 + Code 05 + Code 06 + Code 07.
Indirect method cash flow statement
Determines and calculates the cash inflows and outflows of operating activities by adjusting the pre-tax operating profit for non-cash items, changes in inventories during the period, receivables and payables of operating activities, and items affecting the cash flows of investing activities.
Advantages:
-
Overcomes the disadvantages of the direct method by clearly showing the relationship between operating results and the operating cash flow results
-
Easier to verify and reconcile with other financial statement data
Line items for preparing the statement:
-
Profit before tax (Code 01): Taken from the Total accounting profit before tax line (Code 50) in the Income Statement for the period.
-
Depreciation of fixed assets and investment property (Code 02): Provided the business can isolate the depreciation included in inventory, this line includes only the depreciation charged to the Income Statement for the period. Otherwise, it includes the depreciation of unsold goods. Figures are taken from account 214 corresponding to accounts 632, 641, 642.
-
Provisions (Code 03): Reflects the impact of making, reversing, and using provisions on cash flows during the reporting period, based on the correspondence of accounts 632, 635, 642 with account 229.
-
Gains or losses from foreign exchange rate differences arising from the revaluation of monetary items denominated in foreign currency (Code 04): Based on the correspondence on account 413 and accounts 635, 515.
-
Gains or losses from investing activities (Code 05): Based on the correspondence of account 911 with accounts 5117, 515, 711, 632, 635, 811.
-
Interest expenses (Code 06): Based on the ledger of account 635 corresponding to account 911.
-
Other adjustments (Code 07): Based on the ledgers of accounts 356, 357.
→ Operating profit before working capital changes (Code 08) = Code 01 + Code 02 + Code 03 + Code 04 + Code 05 + Code 06 + Code 07.
Based on pre-tax profit plus the adjustments, if this figure is negative it is recorded in parentheses (…).
-
Increases or decreases in receivables (Code 09): Based on the total difference between closing and opening balances of accounts 131, 136, 138, 133, 141, 244, 331.
-
Increases or decreases in inventories (Code 10): Based on the total difference between closing and opening balances of accounts 151 through 158.
-
Increases or decreases in payables (Code 11): The difference between closing and opening balances of accounts 331, 333, 334, 335, 336, 337, 338, 344, 131…
-
Increases or decreases in prepaid expenses (Code 12): The difference between closing and opening balances of account 242.
-
Increases or decreases in trading securities (Code 13): Based on the total difference between closing and opening balances of account 121 "Trading securities" during the period.
-
Interest paid on borrowings (Code 14): Taken from the ledgers of accounts 111, 112, 131 corresponding to accounts 335, 635, 242 and related accounts.
-
Corporate income tax paid (Code 15): Taken from the ledgers of accounts 111, 112 corresponding to account 3334.
-
Other cash receipts from operating activities (Code 16): Based on the ledger of the debit side of accounts 111, 112 corresponding to the credit side of accounts 161, 136, 3386…
-
Other cash payments for operating activities (Code 17): Based on the ledger of the credit side of accounts 111, 112, 113 corresponding to accounts 161, 353, 3386…
→ Net cash flow from operating activities (Code 20) = Code 08 + Code 09 + Code 10 + Code 11 + Code 12 + Code 13 + Code 14 + Code 15 + Code 16 + Code 17.
Sample statements
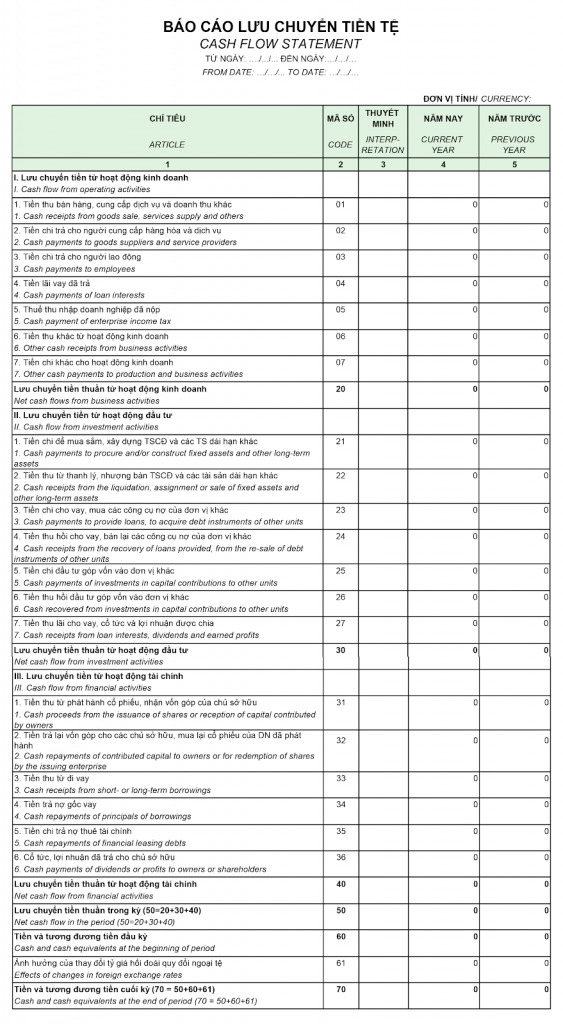
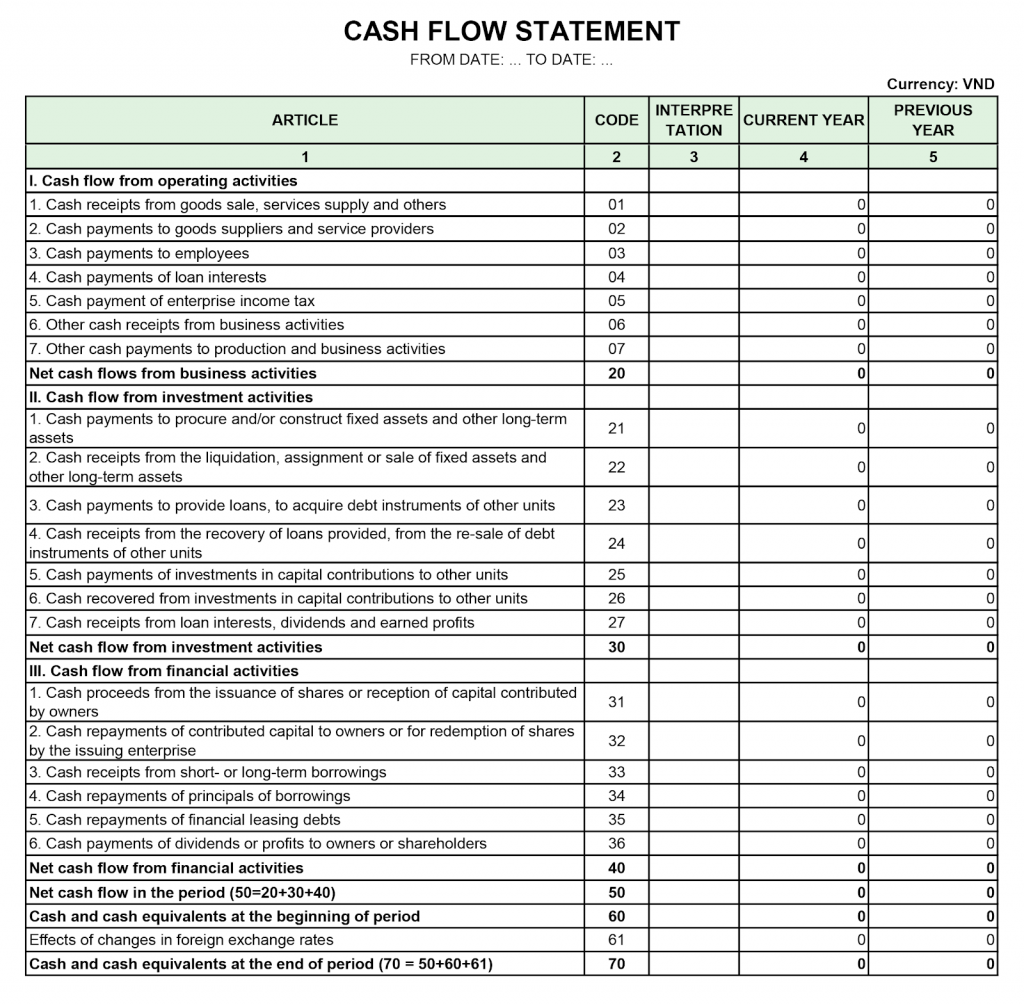
You can refer to the sample cash flow statement illustrations below.
Bilingual Vietnamese – English cash flow statement
Cash flow statement in English
Summary
We hope this article has helped you grasp the fundamentals of the cash flow statement and how to prepare it in line with Circular 200. For businesses to set up, consolidate, and manage financial statements as effectively as possible, accounting and finance management software is the comprehensive solution that simplifies and optimizes the accounting department's reporting workflow.
If you have any questions about preparing the cash flow statement with financial management software, don't forget to visit SimERP accounting software!
Related articles
Bài viết liên quan

25 tháng 10, 2026 · 3 phut doc
2024年网页设计趋势预测如何? | Wotech Electronics
关于 2024 年网页设计趋势——步入 2024 年,年初正是我们为新事物预留时间的时刻。这也非常适合设计师群体唤醒我们内心的"艺术之魂"。闲话不多说,快来和 Markdao 一起浏览 2024 年的 UX/UI 设计趋势吧,说不定您就能为自己接下来的网页设计项目"迸发"出一个绝妙的点子呢!

25 tháng 10, 2026 · 1 phut doc
什么是网站(Website)?网站的详细定义及其带来的商业价值
什么是网站(https://www.markdao.com.vn/blog/website-la-gi)——这个问题或许已经无需定义,因为在如今这个信息时代,网站对每一家企业而言都是不可或缺的组成部分。正是网站帮助用户更近距离地接触企业所提供的产品和服务,从而提升经营效益。此外,要在当今竞争如此激烈的环境中求发展,网站是一个重要因素,它将带你走向品牌与销量上的双重成功。

25 tháng 10, 2026 · 1 phut doc
什么是SEO标准网站?一场"打赢"Google SEO标准的战役 | Wotech Electronics
99%的用户在购买前会先搜索信息,73%的用户只会访问排名前10的网站,并认定它们是值得信赖的品牌……在数字营销爆发的时代,这些数字有力地印证了SEO标准网站的重要性。然而,许多人对什么是SEO标准网站(https://www.markdao.com.vn/blog/huong-dan-toi-uu-seo-website-chuan-seo-on-page)仍然相当模糊,并未真正理解。达到SE…