How to File VAT, PIT, and CIT Tax Reports Monthly, Quarterly, and Annually | Wotech Electronics
Vũ Khôi
Tác giả tại Wotech Electronics Blog
How to File VAT, PIT, and CIT Tax Reports Monthly, Quarterly, and Annually
Vũ Khôi
Author at Wotech Electronics Blog
Tax reports reflect the tax accounting transactions that arise as well as the business situation of an enterprise. There are 3 common types of reports: value-added tax (VAT), personal income tax (PIT), and corporate income tax (CIT) reports. Depending on the characteristics of the enterprise, tax reports are prepared in different forms and on different cycles. Let's look at how to prepare monthly, quarterly, and annual tax reports.
What is a tax report?
A tax report is a report reflecting recurring or periodic tax accounting transactions, which helps the tax authority understand the business situation of an enterprise. There are 3 commonly seen types of tax reports: the corporate income tax report, the value-added tax report, and the personal income tax report. Tax reports can be prepared monthly, quarterly, or annually, depending on the enterprise.
How to prepare tax reports in detail
Each type of tax report has its own characteristics. Accountants need to fully understand how to prepare corporate tax reports to ensure all required information is recorded.
How to prepare a value-added tax (VAT) report
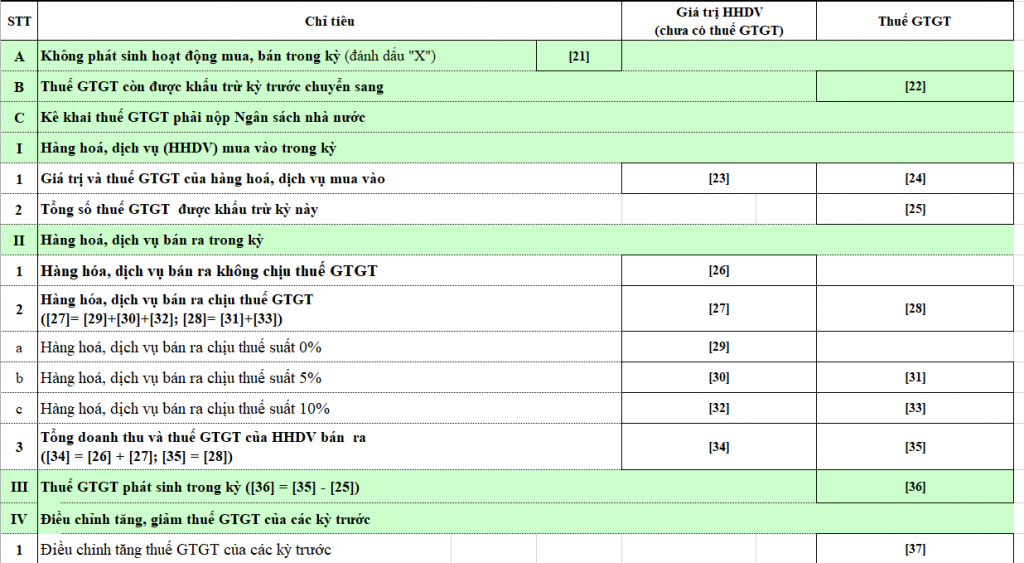
Before starting on the tax report, a business must determine whether to declare VAT monthly or quarterly. Newly established businesses choose to file VAT reports quarterly. For businesses already in operation, the decision is based on the previous year's revenue. If revenue is under VND 50 billion, the monthly VAT report form is used. For businesses with revenue above VND 50 billion, VAT is declared monthly. Basically, the monthly and quarterly VAT filing procedures contain the same items and differ only in whether the detailed figures are recorded by month or by quarter.
Next, the business needs to determine whether to declare VAT under the deduction method or the direct method. The deduction method applies to businesses with revenue of VND 1 billion or more that voluntarily register for it, while the direct method applies to businesses with revenue under VND 1 billion that voluntarily register for it.
Filing VAT under the deduction method
The VAT report under the deduction method is prepared using VAT declaration form No. 01/GTGT. Specifically, the report consists of 3 main sections: the line items, the value of goods and services, and the VAT amount. The line-item section is divided into goods and services sold, goods and services purchased, and other appendices. Under this method, the deadline for the monthly VAT report is the 20th day of the following month, while the quarterly VAT report must be submitted no later than the 30th day of the following quarter.
Filing VAT under the direct method
Businesses use form 4/GTGT for the VAT report under the direct method. When declaring under this method, the business needs to determine the VAT payable. The VAT payable equals revenue multiplied by the percentage rate. Revenue in this case is the total amount actually invoiced from the sale of goods and services. The percentages applied to revenue are as follows:
-
Distribution and supply of goods: 1%
-
Construction services excluding materials: 5%
-
Production and supply of goods associated with construction, including materials: 3%
-
Other activities: 2%
As with the deduction method, the monthly VAT report must be submitted no later than the 20th day of the following month, and the quarterly VAT report no later than the 30th day of the first month of the following quarter. Therefore, accountants must be clear on the deadlines and the monthly or quarterly filing procedures to avoid errors and late submissions.
How to prepare a personal income tax (PIT) report
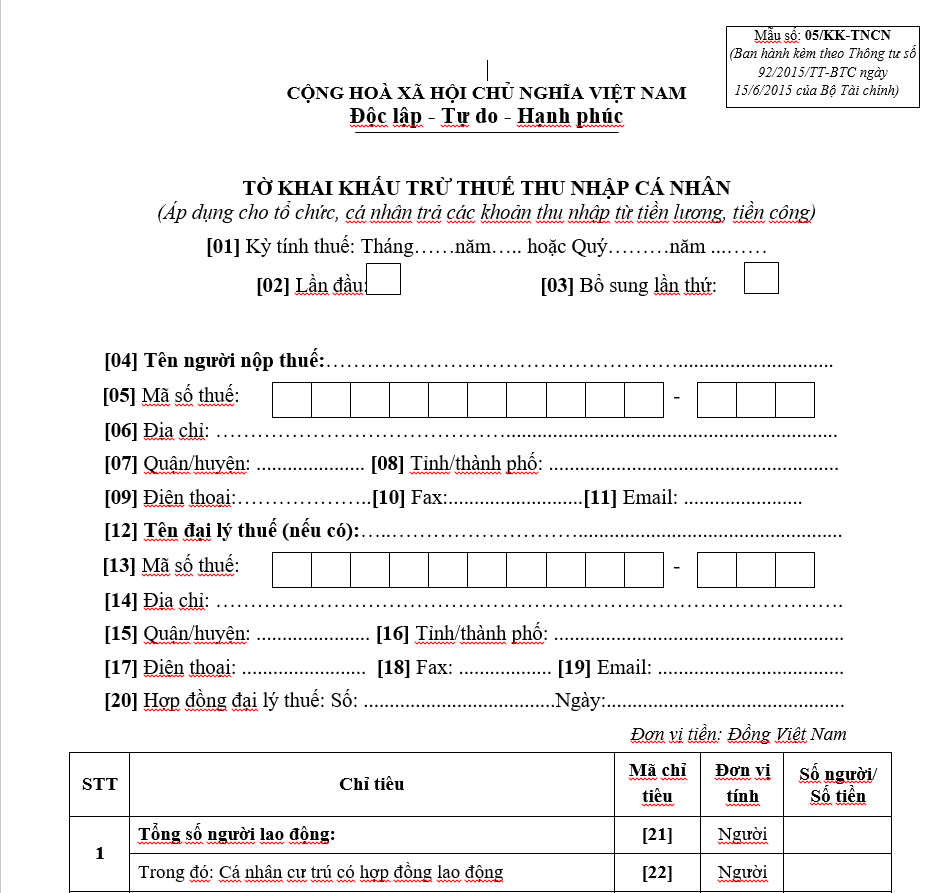
Similar to the VAT report, a business needs to determine whether to declare its PIT report monthly or quarterly. As a rule, if the business declares VAT quarterly, then PIT is also declared quarterly. For businesses that declare VAT monthly, the PIT declaration form is determined as follows:
-
If the PIT arising in a month is VND 50,000,000 or more, the business declares PIT monthly.
-
If the PIT arising in a month is under VND 50,000,000, the business declares PIT quarterly.
Businesses use declaration form 5/KK-TNCN to declare PIT. The monthly and quarterly PIT filing procedures cover the same line items. Specifically, the report form includes the following 11 items:
-
Item 21: Total number of employees.
-
Item 22: Resident individuals with labor contracts.
-
Item 24: Total number of individuals subject to withholding — resident individuals.
-
Item 25: Total number of individuals subject to withholding — non-resident individuals.
-
Item 27: Total PIT taxable income paid to individuals — resident individuals. Taxable income is calculated by taking total income minus tax-exempt amounts.
-
Item 28: Total PIT taxable income paid to individuals — non-resident individuals.
-
Item 30: Total taxable income payable to individuals subject to tax withholding — resident individuals.
-
Item 31: Total taxable income payable to individuals subject to tax withholding — non-resident individuals.
-
Item 33: Total personal income tax withheld — resident individuals.
-
Item 34: Total personal income tax withheld — non-resident individuals.
-
Item 35: Total PIT from life insurance premiums and other non-compulsory insurance.
How to prepare a corporate income tax (CIT) report
The CIT report is prepared using declaration forms 03/TNDN and 03-1A/TNDN (the accompanying appendix). In addition, if the business is profitable and carries forward losses, appendix form 03-2A/TNDN is used as well. CIT reports can be prepared monthly, quarterly, or annually. Basically, the monthly, quarterly, and annual procedures are similar.
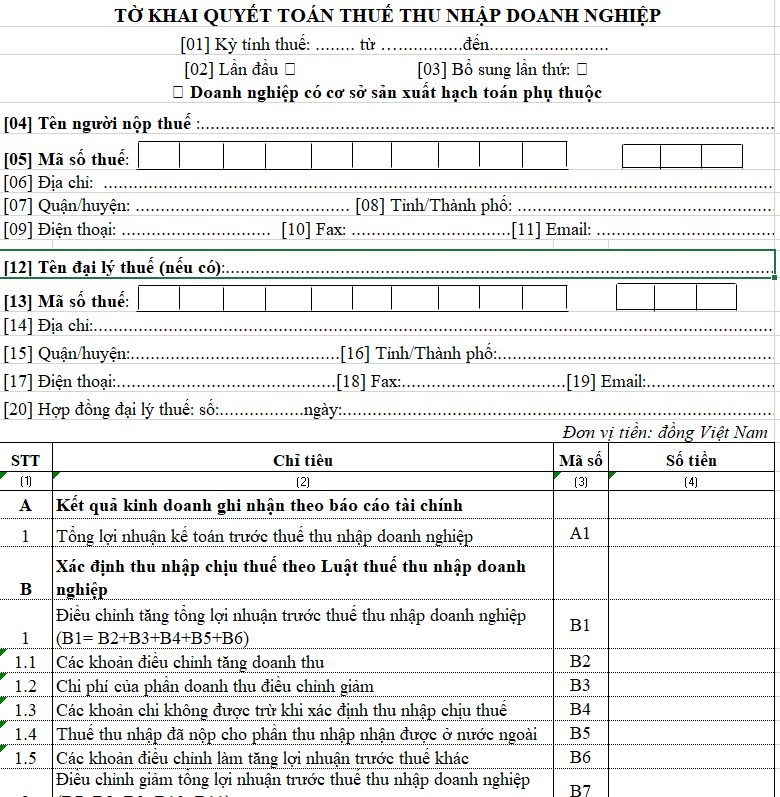
For form 03/TNDN, the business needs to ensure the following 7 main contents:
-
Business results recorded in the financial statements.
-
Determination of taxable income under corporate income tax law.
-
Determination of income tax payable from business operations.
-
Total CIT payable.
-
CIT already paid during the year.
-
Remaining CIT payable.
-
20% of the tax the company must pay.
-
The difference between the remaining CIT and 20% of the CIT payable.
For appendix form 03-1A/TNDN, the business needs to fully declare the following 13 items:
-
Item 02: Revenue from the export of goods and services.
-
Item 04: Trade discounts.
-
Item 05: Sales allowances.
-
Item 06: Value of returned goods.
-
Item 07: Special consumption tax, export tax, and VAT under the direct method.
-
Item 08: Revenue from financial activities.
-
Item 10: Cost of goods sold.
-
Item 11: Selling expenses.
-
Item 12: Administrative expenses.
-
Item 13: Financial expenses.
-
Item 14: Interest expenses on loans used for production and business.
-
Item 16: Other income.
-
Item 17: Other expenses.
How to file tax reports online
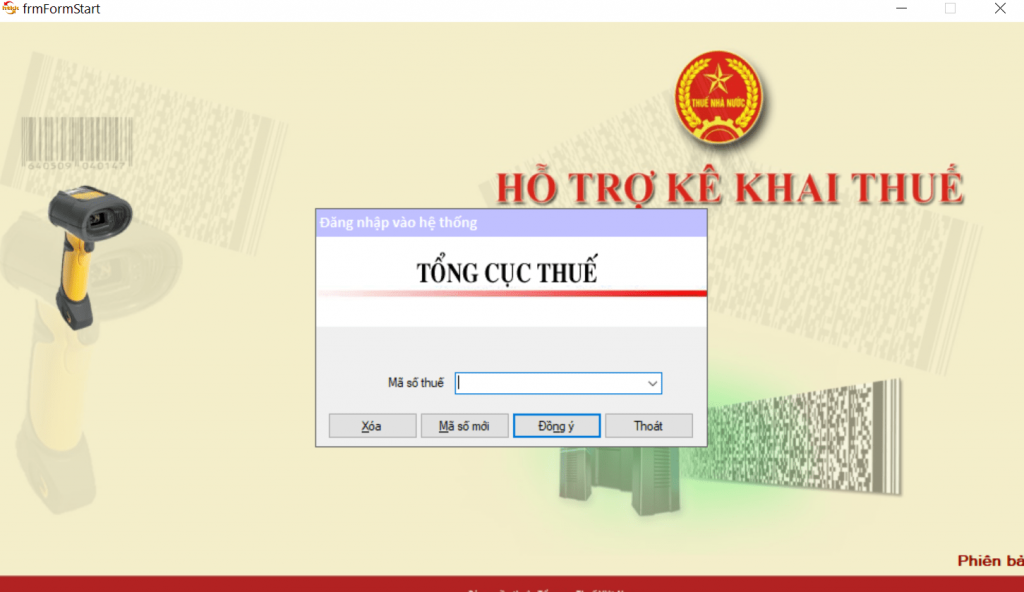
Corporate tax reports are nothing new to businesses, but many accountants still are not fully clear on how to prepare tax reports for their company. One of the main reasons is that tax reports involve many forms and line items. In addition, preparing tax reports manually brings numerous drawbacks: they are hard to store, prone to data errors, and lack continuity. One effective approach a business can adopt is filing tax reports online. Today, the declaration support software (HTKK) released by the General Department of Taxation includes all the required report forms. Accountants can prepare tax reports with just a few simple operations. To prepare a tax report in the HTKK software, the business follows these steps:
-
Log in to the HTKK software.
-
For CIT: go to "Corporate Income Tax" -> Annual CIT finalization (03/TNDN) -> select the tax period.
-
For PIT: go to Personal Income Tax -> 05/KK-TNCN PIT withholding declaration (TT92/2015).
-
For VAT: go to "Value-Added Tax" -> VAT declaration on revenue (04/GTGT).
Related Articles
Bài viết liên quan

25 tháng 10, 2026 · 3 phut doc
2024年网页设计趋势预测如何? | Wotech Electronics
关于 2024 年网页设计趋势——步入 2024 年,年初正是我们为新事物预留时间的时刻。这也非常适合设计师群体唤醒我们内心的"艺术之魂"。闲话不多说,快来和 Markdao 一起浏览 2024 年的 UX/UI 设计趋势吧,说不定您就能为自己接下来的网页设计项目"迸发"出一个绝妙的点子呢!

25 tháng 10, 2026 · 1 phut doc
什么是网站(Website)?网站的详细定义及其带来的商业价值
什么是网站(https://www.markdao.com.vn/blog/website-la-gi)——这个问题或许已经无需定义,因为在如今这个信息时代,网站对每一家企业而言都是不可或缺的组成部分。正是网站帮助用户更近距离地接触企业所提供的产品和服务,从而提升经营效益。此外,要在当今竞争如此激烈的环境中求发展,网站是一个重要因素,它将带你走向品牌与销量上的双重成功。

25 tháng 10, 2026 · 1 phut doc
什么是SEO标准网站?一场"打赢"Google SEO标准的战役 | Wotech Electronics
99%的用户在购买前会先搜索信息,73%的用户只会访问排名前10的网站,并认定它们是值得信赖的品牌……在数字营销爆发的时代,这些数字有力地印证了SEO标准网站的重要性。然而,许多人对什么是SEO标准网站(https://www.markdao.com.vn/blog/huong-dan-toi-uu-seo-website-chuan-seo-on-page)仍然相当模糊,并未真正理解。达到SE…